
How to Calculate Actual Business Profit: A Guide for SMEs
November 17, 2026
How to Prepare Monthly Management Reports: A Practical Guide for Small Business Owners
November 18, 2026
Do you want to know how to Identify Cash Flow Problems in Your Business Before They Become a Crisis?
Your business is making sales. Customers are placing orders. Money is entering your bank account.
Yet, somehow, you still struggle to pay salaries, suppliers, rent, and other business expenses. What exactly is going wrong?
You may not have a sales problem. You may have a cash flow problem!
One of the biggest mistakes small business owners make is assuming that increased sales automatically mean increased cash. Unfortunately, this is not always true. A business can be profitable on paper and still struggle to meet its daily financial obligations.
For many Nigerian SMEs, this situation is becoming increasingly challenging due to rising operating costs, inflation, delayed customer payments, high inventory costs, and poor financial record-keeping.
But here is the good news: Cash flow problems rarely appear without warning. There are signs you can identify early enough to take corrective action before your business runs into a financial crisis.
In this article, you will discover how to identify cash flow problems, the warning signs to watch out for, what causes them, and practical steps you can take to improve your business cash flow.
If your business generates revenue but you constantly wonder where the money goes, keep reading. This could be the financial wake-up call your business needs.
Learn how to Calculate Actual Business Profit.
What Is Cash Flow?
Cash flow refers to the movement of money into and out of your business over a particular period.
Cash inflows are the money entering your business, including:
- Payments received from customers.
- Cash sales and online transfers.
- Business loans and investments.
- Other business income.
Cash outflows are the money leaving your business, including:
- Payments to suppliers.
- Staff salaries and wages.
- Rent, electricity, and other utility bills.
- Transportation and logistics.
- Loan repayments and interest.
- Taxes and statutory obligations.
- Other operating expenses.
Your business has positive cash flow when more cash comes in than goes out during a given period. Negative cash flow occurs when more cash leaves the business than enters it.
However, negative cash flow does not necessarily mean your business is failing. It becomes a serious concern when the business cannot generate or access enough cash to meet its financial obligations when they fall due.
10 Warning Signs That Your Business Has a Cash Flow Problem
How do you know when your business is experiencing cash flow difficulties?
Here are ten practical warning signs every business owner should pay attention to.
1. You Constantly Struggle to Pay Business Expenses
Do you regularly struggle to pay salaries, suppliers, rent, electricity bills,s or other operating expenses?
Do you sometimes postpone payments because there is insufficient money in your business account?
This is one of the clearest indications of a cash flow problem.
Even when your business is making sales, the timing of customer payments may not align with your payment obligations.
For example, your business may supply goods worth ₦2 million to a customer on 30-day credit terms. However, your suppliers require payment within seven days.
This creates a cash gap that your business must finance.
What to do: Review your payment obligations and customer collection periods. Negotiate better payment terms with suppliers and introduce more effective customer payment follow-up procedures.
2. Your Customers Owe You Too Much Money
Outstanding customer invoices can silently destroy your business cash flow.
You may have completed several transactions, issued invoices, and recorded substantial revenue. However, until customers pay, that money is not available to fund your operations.
For example, imagine your business has outstanding customer invoices of ₦5 million, but only ₦500,000 in the bank.
You may appear financially successful based on your sales figures, but your ability to operate depends on when those customers actually pay.
What to do:
- Maintain an updated accounts receivable schedule.
- Follow up on overdue invoices.
- Establish clear credit policies.
- Request deposits or part-payments before delivering goods or services.
- Stop extending credit to customers with a history of delayed payments.
3. You Frequently Borrow Money to Run Daily Operations
Borrowing is not necessarily bad for a business. Loans can support expansion, equipment purchases, and other strategic investments.
However, if you constantly borrow money to pay salaries, purchase inventory, or settle routine operating expenses, your business may have a structural cash flow problem.
Using new loans to settle old debts can create a dangerous financial cycle.
Before taking another loan, determine why your business cannot generate enough cash to sustain its daily operations.
What to do: Prepare a cash flow forecast to identify when cash shortages are likely to occur. Review operating expenses, customer collections, and inventory levels before considering additional borrowing.
4. Your Sales Are Increasing, But Your Bank Balance Is Not
This is one of the most confusing situations for business owners.
Your business is attracting more customers, making more sales, es and expanding operations. Yet, your bank balance remains low.
Why?
Because increased sales can also result in increased expenses.
You may be spending more on inventory, transportation, salaries, marketing, credit sales, and other operating costs.
If customers are not paying quickly enough, your business could be growing faster than its cash resources can support.
What to do: Monitor cash generated from operations, not just sales revenue. Evaluate whether increased sales are translating into actual cash collections and sustainable margins.
5. You Cannot Easily Determine Where Your Money Goes
If you cannot explain how your business spends its money, you may have a serious financial visibility problem.
Some business owners mix personal and business expenses, make withdrawals without documentation, or pay for business expenses without maintaining proper records.
As a result, they struggle to identify unnecessary spending and determine how much cash is available.
What to do:
- Separate personal and business finances.
- Record every business transaction.
- Review expenses weekly.
- Reconcile your bank accounts regularly.
- Prepare monthly management accounts.
Good financial records help you understand where your money goes and identify opportunities to reduce unnecessary spending.
6. Your Inventory Is Tying Down Too Much Cash
For businesses involved in trading, manufacturing, hospitality and food services, inventory management has a significant impact on cash flow.
Excessive inventory means money is sitting in goods that have not yet been converted into sales.
For example, a restaurant that purchases more food items than it can sell within a reasonable period may experience spoilage, wastage, and cash shortages.
Similarly, a retail business holding slow-moving products may struggle to generate enough cash to replenish fast-selling items.
What to do:
- Identify fast-moving and slow-moving inventory.
- Monitor inventory turnover.
- Avoid unnecessary bulk purchases.
- Introduce regular stock counts.
- Improve purchasing and demand forecasting.
Remember, inventory is an asset, but it cannot pay your bills until it is converted into cash.
7. You Regularly Delay Supplier Payments
Are your suppliers constantly calling to demand payment?
Do you sometimes delay payments beyond agreed credit periods because you do not have sufficient cash?
This could indicate that your business is struggling to manage its working capital.
Late supplier payments can damage business relationships, reduce your purchasing power and cause suppliers to withdraw favourable credit terms.
What to do: Develop a supplier payment schedule, prioritise critical obligations and negotiate payment terms that align with your customer collection cycle.
8. You Depend on Personal Money to Keep the Business Running
A business that constantly depends on the owner’s personal savings to survive may not be financially sustainable.
If you regularly transfer personal money into your business account to pay suppliers, salaries, and other operating expenses, you need to investigate the underlying problem.
The business may have low profit margins, excessive operating costs, poor debt collection, or inefficient working capital management.
What to do: Separate personal and business finances, establish a realistic business budget, and evaluate whether the business generates sufficient cash from its normal operations.
9. You Have No Clear Idea How Much Cash Will Be Available Next Month
If you only check your bank balance when you need to make payments, you are managing your finances reactively.
Successful cash flow management requires you to anticipate future cash inflows and outflows.
For example, you should know:
- How much money customers are expected to pay next week.
- Which suppliers must be paid.
- When salaries and rent are due.
- How much inventory you need to purchase.
- What taxes and loan repayments are approaching.
Without this information, you may be caught off guard by expenses you should have anticipated.
What to do: Prepare a rolling 13-week cash flow forecast and update it regularly.
10. You Frequently Experience Emergency Cash Shortages
Does your business experience unexpected cash shortages almost every month?
Do you constantly have to look for emergency funds to meet financial obligations?
This suggests that your business may not have adequate cash reserves or a reliable cash flow management system.
Unexpected expenses are part of doing business. However, recurring emergencies often indicate weaknesses in financial planning.
What to do: Establish a business cash reserve, prepare cash flow projections, and identify the periods when your business is most likely to experience cash shortages.
Check out: How to Manage Cash Flow Effectively: Tips and Tools
What Causes Cash Flow Problems in Small Businesses?
Identifying the warning signs is important, but understanding the underlying causes is equally essential.
Some common causes of cash flow problems among SMEs include:
- Poor financial record-keeping: Without accurate records, business owners cannot properly monitor cash inflows, outflows, and outstanding obligations.
- Excessive operating expenses: Uncontrolled spending on salaries, rent, logistics, utilities, and other expenses can consume available cash.
- Poor credit management: Selling goods and services on credit without effective collection procedures delays cash inflows.
- Inadequate cash flow forecasting: Businesses that do not plan their future cash requirements are more likely to experience unexpected shortages.
- Poor inventory management: Overstocking, expired goods, damaged products, and slow-moving inventory tie down valuable cash.
- Low profit margins: A business may generate substantial revenue but retain very little after covering its costs.
- Mixing personal and business finances: Uncontrolled personal withdrawals make it difficult to determine the actual financial position of the business.
- Unplanned business expansion: Expanding operations without adequate working capital can put pressure on available cash.
Understanding these causes helps you address the real problem instead of constantly looking for emergency funds.
👉 Take control of your cash flow today.
GET THE SME CASH FLOW SURVIVAL TOOLKIT™ and discover the practical financial survival system that helps Nigerian SME owners recover trapped money, control expenses, improve cash flow, and build a financially stable business even if you don’t have an accounting background.
How to Check Whether Your Business Has a Cash Flow Problem
You do not need an expensive financial system to conduct an initial cash flow health check.
Start with these five practical steps.
Step 1: Check Your Available Cash
Determine how much cash your business currently has in its bank accounts and petty cash.
Do not rely on sales figures or expected customer payments. Focus on money that is actually available.
Step 2: List All Outstanding Customer Payments
Prepare a schedule of customers who owe your business money.
Include:
- Customer names.
- Invoice numbers.
- Outstanding amounts.
- Invoice dates.
- Due dates.
- Number of days overdue.
This will help you identify overdue debts and prioritise collections.
Step 3: Identify All Outstanding Business Obligations
List all payments your business is expected to make within the next 30 days.
Include suppliers, salaries, rent, utilities, taxes, loan repayments, and other commitments.
Step 4: Compare Expected Cash Inflows with Cash Outflows
Calculate the difference between expected cash receipts and planned payments.
For example:
| Description | Amount |
|---|---|
| Opening cash balance | ₦1,000,000 |
| Expected customer collections | ₦2,500,000 |
| Total available cash | ₦3,500,000 |
| Supplier payments | ₦1,500,000 |
| Salaries | ₦800,000 |
| Rent and utilities | ₦400,000 |
| Other operating expenses | ₦600,000 |
| Total expected payments | ₦3,300,000 |
| Projected closing cash balance | ₦200,000 |
In this example, the business is expected to close the period with ₦200,000.
Although the balance is positive, it may be insufficient to cover unexpected expenses or additional obligations.
Step 5: Prepare a Cash Flow Forecast
Use your available information to project cash inflows and outflows for the next 4 to 13 weeks.
This will help you identify potential cash shortages before they happen and take corrective action early.
7 Practical Ways to Improve Your Business Cash Flow
Once you identify the problem, the next step is to implement practical solutions.
Here are seven strategies you can start applying immediately.
1. Improve customer debt collection. Follow up on overdue invoices, introduce payment reminders, and establish clear credit policies.
2. Control unnecessary expenses. Review your operating costs and eliminate expenses that do not contribute meaningfully to business performance.
3. Manage inventory efficiently. Purchase according to demand, monitor stock movement, and reduce money tied up in slow-moving inventory.
4. Negotiate better supplier payment terms. Where possible, negotiate payment periods that give you enough time to collect money from customers.
5. Prepare weekly cash flow forecasts. Stop relying on your bank balance alone. Know what is expected to come in and go out.
6. Separate personal and business finances. Establish clear withdrawal policies and pay yourself through a structured arrangement.
7. Maintain a cash reserve. Build an emergency fund to help your business manage unexpected expenses and temporary cash shortages.
Why Every SME Needs a Cash Flow Management System
Running a business without monitoring cash flow is like driving a vehicle without checking the fuel gauge.
You may continue moving for a while, but eventually, you could run out of fuel when you least expect it.
A proper cash flow management system helps you:
- Understand your actual cash position.
- Identify potential financial problems early.
- Plan supplier and salary payments.
- Reduce unnecessary expenses.
- Improve customer debt collection.
- Make better purchasing decisions.
- Prepare for business expansion.
- Maintain financial stability.
You do not have to wait until your business is experiencing a financial crisis before taking cash flow management seriously.
The earlier you identify the problem, the easier it becomes to implement corrective measures.
Take Control of Your Business Finances with the SME Cash Flow Survival Toolkit™
What if you could finally understand where your business money goes, identify cash shortages before they happen,n and take practical steps to improve your financial position?
That is exactly why we created the SME Cash Flow Survival Toolkit™.
This practical financial management resource is designed to help Nigerian small business owners take control of their finances without needing to become professional accountants.
Instead of struggling with complicated financial concepts, you get practical tools and templates that help you manage your business cash flow more effectively.
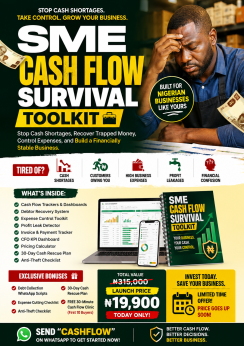
How to Stop Cash Shortages, Control Expenses, Recover Lost Profits, Improve Cash Flow, and Build a Financially Stable Business Without Being an Accountant
What You Will Get Inside the Toolkit
- Practical Cash Flow Management Guide: Understand how to monitor and manage money coming into and going out of your business.
- Excel Cash Flow Templates: Track your income, expenses, and cash position.
- Cash Flow Dashboard: Get a clearer picture of your business’s financial performance.
- Expense Tracking Tools: Identify where your money goes and uncover unnecessary spending.
- Debtor Management Templates: Monitor outstanding customer payments and improve debt collection.
- 30-Day Cash Flow Improvement Plan: Follow a practical action plan to strengthen your business finances.
- Bonus Emergency Cash Flow Action Plan: Know what to do when your business is facing a cash shortage.
- Bonus Debtor Follow-Up Scripts: Communicate professionally with customers who owe your business money.
- Bonus Expense Reduction Checklist: Identify opportunities to reduce unnecessary business costs.
- Bonus Weekly Financial Review Template: Build a consistent habit of monitoring your business finances.
Who Should Get This Toolkit?
This toolkit is particularly useful for:
- Small and medium-sized business owners.
- Retail and wholesale business operators.
- Restaurant and food business owners.
- Hospitality and hotel operators.
- Service-based businesses.
- Entrepreneurs who struggle with financial record-keeping.
- Business owners who generate sales but frequently experience cash shortages.
You do not need to wait until your business is in financial trouble before getting the tools to manage your money better.
Your business deserves more than just making sales. It deserves financial stability.
Get Your SME Cash Flow Survival Toolkit Today!
Stop guessing where your money goes. Start tracking, planning, ng and managing your business cash flow with practical tools designed for Nigerian SMEs.
Click the link below to get instant access to the SME Cash Flow Survival Toolkit™:
👉 https://selar.com/yhu5e4q2ns
Take the first step towards building a financially stronger and more sustainable business.
Conclusion
Cash flow problems can affect businesses of every size, including businesses with impressive sales figures and seemingly healthy profits.
The difference between businesses that survive financial difficulties and those that struggle is often their ability to identify warning signs early and take corrective action.
Do not wait until you cannot pay your suppliers, staff, or other business obligations before reviewing your finances.
Start monitoring your cash flow today. Keep accurate financial records, collect customer payments promptly, control expenses and plan your future cash requirements.
Remember: Revenue keeps your business busy, profit makes it worthwhile, but cash flow keeps it alive.
Need Professional Help Managing Your Business Finances?
At Skypro Professional Services, we help SMEs improve financial visibility, strengthen internal controls, manage working capital, and build more effective financial management systems.
Whether you need bookkeeping, management accounts, cash flow reviews, internal controls, or financial advisory services, our team can help.
Visit https://skyproservices.com.ng or contact us to discuss how we can support your business.
Skypro Professional Services – Helping Businesses Operate Smarter, Grow Faster and Stay Financially Strong.
Are You Really Making Money in Your Business?
Download your FREE Business Profit Calculator and discover how much your business actually earns after expenses.
Stop guessing. Start calculating. Take control of your business finances.
FREE Excel Calculator – Designed for Nigerian SMEs.
#BusinessProfitability #SMEs #SmallBusinessNigeria #FinancialManagement #BusinessGrowth #Accounting #SkyproProfessionalServices #howtoidentifycashflowproblems #howtoidentifycashflowleakages


